

Time to Pay Arrangements (TTP)



A Time to Pay arrangement is an instalment plan with HMRC for an overdue tax bill. There is no fixed maximum term, because HMRC sets the length by what you owe and what you can afford, but for a company it will want the debt cleared as fast as the business can realistically manage.
We help directors negotiate TTP arrangements with HMRC, and timing matters for a plain reason. Before enforcement starts, the only question HMRC is asking is whether your plan is affordable.
Leave it until penalties have been added and a statutory demand (a formal demand to pay within 21 days, the usual step before a winding-up petition) has been served, and the same request now has to persuade HMRC to pause recovery action it has already started.
Quick Answer: How HMRC Time to Pay Works
Start with HMRC’s online payment plan service, because if your debt qualifies you can set the plan up without a phone call. The service needs your returns filed and no other HMRC plan in place, and for Self Assessment the online limit is £30,000. For VAT and PAYE it checks whether you qualify once you sign in.
If the online route does not fit your debt, call the HMRC payment line for the tax you owe. The letter HMRC sent you names the tax and gives its reference number, so have it in front of you when you ring. HMRC lists these lines as open Monday to Friday, 8am to 6pm, closed on bank holidays:
- VAT: 0300 200 3831
- Employer PAYE: 0300 200 3819
- Corporation Tax: 0300 200 3840
- Self Assessment: 0300 200 3820, or 0300 123 1813 if you owe more than £30,000
Before you ring, work out a monthly figure the company can keep paying alongside its new tax bills; the checklist below shows what HMRC will ask for. Our HMRC contact guide lists the other HMRC lines.
Once HMRC agrees a plan, it holds off recovery action on that debt while you pay. You still have to meet each new tax bill on time.
Interest continues to accrue on the outstanding balance at the HMRC late-payment rate (Bank of England base rate plus 4%, since 6 April 2025).
If you miss a payment, HMRC says it will contact you and try to rearrange the plan where it can. That is not a promise. If the plan cannot be put back on track, HMRC can ask for the full balance and restart recovery.
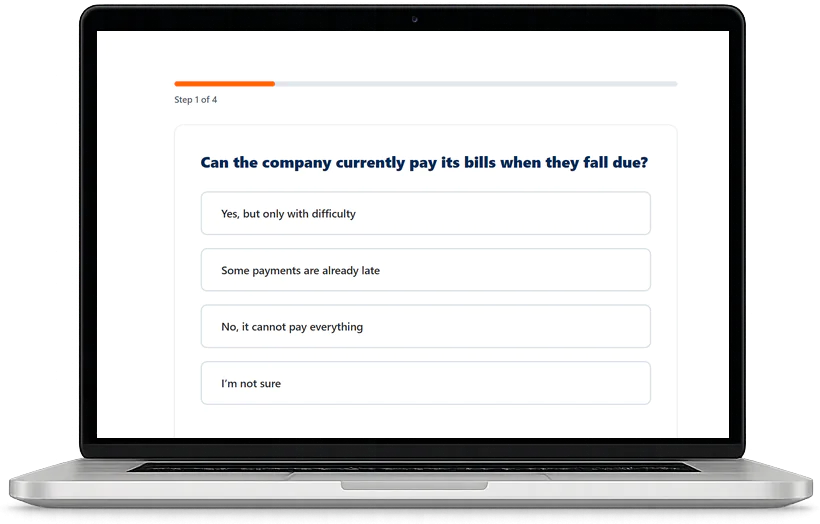
Could Your Company Be Insolvent?
Answer four short questions to see which warning signs apply, how serious the position may be and how soon you may need to act.
See which options may fit your company’s circumstances.
Check my company’s positionSee your result online and receive a copy by email. We only call if you ask.
Which Tax Debts Qualify for HMRC Time to Pay?
TTP is available for all HMRC business tax debts. The five most common are below.
- VAT: quarterly or monthly returns.
- PAYE and employee NICs: monthly payroll deductions. HMRC treats these as money you collected on its behalf and negotiates least flexibly.
- Corporation Tax: annual company tax. HMRC is more flexible here because the debt is the company’s own.
- CIS deductions: Construction Industry Scheme payments.
- Self Assessment: personal tax for directors paid through SA.
HMRC treats different tax types with different urgency, and the reason matters when you decide which TTP to ask for first.
PAYE and employee NICs are pursued hardest because HMRC treats these as money the company collected from employees and held as a fiduciary, not as a company debt. VAT sits in the middle for similar reasons: collected from customers and remitted on. Corporation Tax sits at the other end, since nobody else’s money was collected to create it.
If you owe more than one tax type, request the TTP for Corporation Tax first while you sort current PAYE and VAT, not the other way round.
How to Negotiate an HMRC Time to Pay Arrangement
Before You Call HMRC
- Know exactly what you owe. Check your Business Tax Account at tax.service.gov.uk; the balance updates daily.
- Prepare a breakdown of your company’s monthly income and expenses. The HMRC adviser will ask for this.
- Have a realistic repayment proposal ready. Not what you hope to pay. What you can guarantee.
- Decide what you will put in personally before HMRC asks. Its guidance says it expects a company to reduce the debt first, by releasing assets such as stock and vehicles, and it may ask directors to put personal funds into the business or take on lending. Money you lend a struggling company may not come back if it later fails, so settle your limit before the call, not during it.
- Make sure your tax returns are filed up to date. HMRC will normally expect outstanding returns to be filed before it agrees a TTP, because it needs them to confirm the total debt. If you cannot pay the tax shown on the return, file the return anyway and call about the TTP straight after. Filing first is what unlocks the conversation.
On the Call With HMRC
- Be honest about why you cannot pay. HMRC hears every excuse. Honesty builds credibility.
- Propose a specific monthly amount and duration. “I can pay £3,000 per month for 10 months” lands better than “I need help.”
- Confirm you can meet current obligations during the TTP. This is non-negotiable. If you cannot pay the old debt and keep up with new liabilities, TTP is not viable.
- Ask for the agreement in writing. HMRC will send a confirmation letter. Keep it.
HMRC’s guidance says it will ask a company how it can pay as quickly as it can, then question the proposal to check it is realistic. So the length is not something you pick. A longer plan needs more evidence that the business can carry it alongside its new tax bills.
What Happens If HMRC Rejects Your Time to Pay Application
HMRC rejects TTP when they conclude the business is not viable, the proposed repayment is unrealistic, or you have a history of broken arrangements. Rejections are most likely in the four situations below.
| Reason for rejection | What it usually means |
|---|---|
| Director called too late | Enforcement has already started; HMRC has lost confidence in the company’s ability to pay. |
| Multiple tax types overdue | The arrears across VAT, PAYE, and CT together suggest the business is structurally insolvent, not cash-strapped. |
| Previous TTP broken | HMRC’s system records every prior arrangement. A broken TTP is treated as a credibility problem. |
| Numbers do not support the proposal | The income and expenses breakdown shows the company cannot sustain the proposed repayments. |
There is no formal appeal against a refusal. HMRC’s guidance says you can complain about how you were treated, but not challenge the decision itself, so the way forward is a better proposal rather than an argument.
A rejection narrows the options in a specific order. The cheapest move is to propose revised terms straight back: a lower monthly amount, a longer period, or both.
The next step is to engage a licensed insolvency practitioner to make the call, because HMRC sometimes responds differently to a regulated firm putting forward a documented assessment of viability.
The third move is a formal restructuring like a CVA. If 75% by value of the creditors who vote approve it, HMRC is bound too, but its preferential VAT and PAYE debts must still be paid ahead of ordinary creditors unless HMRC agrees otherwise.
If none of those work and HMRC proceeds to enforcement, the next step is typically a statutory demand followed by a winding-up petition under section 124 of the Insolvency Act 1986. At that point the question shifts from how to pay the tax to whether to close or save the company, and the calendar is no longer yours.
What Happens During the Time to Pay Period
| What stops | What carries on |
|---|---|
| Enforcement is suspended: no statutory demands, no field officers, no winding-up petitions for the agreed debt. | Interest accrues on the outstanding balance at base rate plus 4% throughout. |
| Most late-payment penalties freeze for the duration. | You must make every TTP payment on time. Miss one and HMRC will contact you to rearrange the plan or ask for the full balance. |
| HMRC will not take enforcement action for the agreed debt while you keep to the schedule, but it can set any tax repayment due to the company against what you owe. | You must meet current tax obligations: this quarter’s VAT, this month’s PAYE, this year’s CT all paid on time. |
The current-obligations requirement is the easiest one to break without noticing. A director negotiates a TTP for last year’s VAT, then misses this quarter’s VAT because the repayments consumed the cash that was supposed to cover the new bill. The TTP terminates and the total debt is now larger than it was at the start.
We stress-test the numbers before we let a director sign. Can the business fund the TTP repayments and meet current obligations from forecast cash? If the answer is no, the TTP is a displacement exercise, not a solution, and the company needs a different conversation.
Time to Pay vs Other HMRC Debt Options
| Option | Best used when | Limit |
|---|---|---|
| Time to Pay | Single or limited HMRC debt, business is otherwise viable, called early. | Only covers HMRC. Will not solve a broader creditor problem. |
| Informal creditor negotiation | You have other creditors beyond HMRC who are open to instalments. | Not legally binding. A single creditor can withdraw and force the issue. |
| Company Voluntary Arrangement | Multiple creditors including HMRC; business viable with restructured debt. | Requires 75% creditor vote; HMRC’s vote often decisive. Failure usually ends in liquidation. |
| Company Administration | HMRC has filed a winding-up petition or business needs the statutory moratorium. | Heavier process; administrator takes control; outcome depends on saleable value. |
| Creditors’ Voluntary Liquidation | HMRC debt is unmanageable and the business cannot be rescued. | Closes the company; preserves IP choice and timing if you act before petition. |
What You Should Do Right Now About HMRC Time to Pay
If you owe HMRC tax and cannot pay it by the deadline, ask for a plan now, online if the debt qualifies or on the payment line for that tax. What you are asking HMRC to agree gets harder with each stage below.
- Before the deadline: you are asking for time on a bill that is not yet late, with no penalties added and nothing in recovery.
- In the first weeks after it: the debt is recent and small, and the online service may still accept it.
- After a few months: interest and penalties have grown the balance, and HMRC’s recovery letters have started.
- After a statutory demand: you are asking HMRC to stop action it has already started, against a 21-day deadline. Get advice the same day.
If you have already been rejected, or if the debt is too large for TTP, Company Debt’s licensed insolvency practitioners can negotiate with HMRC on your behalf or advise on alternative routes. Take our two-minute insolvency test first if you are not sure where the company actually stands. Asking HMRC for time too early costs you nothing but the call.
Frequently Asked Questions About HMRC Time to Pay Arrangements
How long can an HMRC Time to Pay arrangement last?
There is no fixed limit. HMRC’s guidance says the length depends on how much you owe and what you can afford each month, and you can ask to make the plan longer or shorter if your circumstances change.
For a company, HMRC asks how you can pay as quickly as you can, so a plan stretching over years needs a strong explanation. If the only affordable plan is a very long one, read that as a warning about the business, not just about the tax bill.
Does Time to Pay stop penalties and interest?
It does not stop interest. Interest runs for as long as any of the debt is unpaid, which is why HMRC points out that paying faster costs less overall.
Late-payment penalties may be frozen while the TTP is active, depending on the tax type and your compliance history. The TTP stops enforcement action but does not eliminate the cost of being late.
Can I get a second Time to Pay if my first one failed?
Possible, but significantly harder. HMRC’s system records broken arrangements and the adviser will see the history. You will need to explain why the first arrangement failed and demonstrate that circumstances have changed.
A second TTP with professional representation (an IP or tax adviser making the call) sometimes carries more weight than a director calling alone, particularly if the first failure was procedural rather than viability-driven.
Do I need an accountant or IP to negotiate a Time to Pay?
No. You can set the plan up yourself, online if the debt qualifies or by calling the HMRC payment line for that tax. For straightforward arrangements (single tax type, realistic repayment, first-time TTP), the call is simple.
For complex situations (multiple tax types, large debts, previous broken arrangements, or an active statutory demand), professional representation can improve the outcome. The IP makes the same call, but with the credibility of a regulated firm and a documented assessment of the company’s viability.
Will HMRC accept a Time to Pay if I have a personal guarantee on the debt?
HMRC tax debts do not normally involve personal guarantees in the way bank debt does. The relevant personal-liability mechanisms for HMRC are Personal Liability Notices (under the Social Security Administration Act 1992 for unpaid NIC) and Joint and Several Liability Notices (under Finance Act 2020 for tax-avoidance and certain insolvency cases).
A TTP is a company-level arrangement and does not change personal liability under those notices. If a Personal Liability Notice has been issued or is threatened, the conversation needs to cover both the company TTP and the personal exposure separately.
Not Sure Where Your Company Stands?
Use the two-minute test to check the warning signs and see how soon you may need to act.
Check my company’s positionEstimates are fineWe only call if you ask us to
Related Guides
- HMRC Tax Debt Hub: overview of the HMRC debt-collection process and the routes available at each stage.
- Cannot Pay VAT: VAT-specific TTP guidance and risks.
- Cannot Pay PAYE: why HMRC negotiates least flexibly on payroll deductions.
- Problems Paying Corporation Tax: CT-specific TTP and rescue options.
- Winding-Up Petitions: what happens if HMRC moves to enforcement.
- Company Voluntary Arrangement: the route when TTP alone cannot solve the creditor picture.
- 30-Second Insolvency Test: confirm where your company actually stands before negotiating.