


If your company has VAT arrears, meaning VAT it owes HMRC but can’t pay, the most useful thing you can do is talk to HMRC early, ideally before day 15 after the payment deadline. Up to that point, asking for a payment plan that HMRC goes on to agree means no late payment penalty, and after it the penalties start to build.
Two things will make that call easier. File the return, even if you can’t pay what’s on it, because HMRC penalises a late return separately from late payment. Then check the exact balance in the VAT account, so the conversation starts from the real figure rather than a guess.
The call also needs to come before HMRC moves to enforcement, which can mean seizing goods, taking money from the company’s bank account or going to court.
Before or alongside that call, you need to work out whether this is one bad quarter or a sign of something wider. A single missed payment in an otherwise healthy business is a cash-flow problem that HMRC has a standard route for: Time to Pay. Unpaid VAT sitting alongside late PAYE and stretched suppliers is different, because it may mean the company can no longer pay its debts as they fall due.
Can’t Pay VAT? Quick Answer
| Your position | Best first step |
|---|---|
| VAT is only just overdue | Pay if you can, or contact HMRC immediately |
| VAT is more than 15 days overdue | Late payment penalties may now apply, so contact HMRC at once |
| VAT is more than 30 days overdue | Check the penalties and interest already added, and whether an instalment plan is still realistic |
| Several VAT periods are unpaid | Test whether the company can pay the old VAT and the current VAT together |
| VAT plus PAYE, Corporation Tax or suppliers are overdue | Treat it as a possible wider insolvency problem |
| HMRC has threatened enforcement or a winding-up petition (a court application to close the company) | Take insolvency advice immediately |
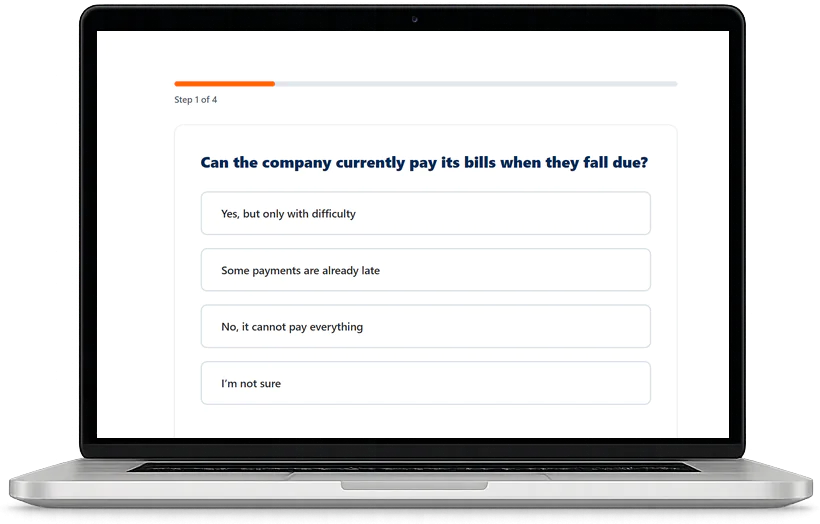
Could Your Company Be Insolvent?
Answer four short questions to see which warning signs apply, how serious the position may be and how soon you may need to act.
See which options may fit your company’s circumstances.
Check my company’s positionSee your result online and receive a copy by email. We only call if you ask.
What Directors Should Do If Your Company Has VAT Arrears
- Submit any outstanding VAT return. Even if you can’t pay what’s on it, a filed return stops a second set of penalties building up, because HMRC charges for late filing and late payment separately.
- Work out exactly what the company owes. The VAT account shows the balance with any penalties and interest already added, and it’s much easier to agree a plan when you and HMRC are looking at the same number.
- Check whether the company can pay in full. That means looking beyond today’s bank balance to the cash you expect over the next three months, including what customers still owe you. If late-paying customers are the reason for the arrears, tell HMRC and give dates. A list of who owes you what, and when it’s due, carries far more weight than a general promise.
- If it can’t, ask HMRC for Time to Pay. HMRC’s own guidance is to get in touch as soon as you know you can’t pay, and a filed return with a specific monthly offer gives the person on the phone something concrete to agree to.
- Make sure the plan survives the next bill. HMRC expects new returns to be paid on time while the old debt is cleared, so an offer has to leave room for this quarter’s VAT as well as last quarter’s, or it will fall over at the next deadline.
- Take insolvency advice if VAT is part of a wider problem. Keep dated notes of your cash forecasts and why you made each decision as you go. If a liquidator ever looks back at this period, those notes are what show what you knew and when.
Can You Get a VAT Time to Pay Arrangement?
A Time to Pay arrangement is HMRC’s instalment plan for tax a company can’t pay in one go. There’s no standard length, because HMRC bases the plan on what the company can afford. Its starting point is that tax should be paid as quickly as the company can manage, so expect to be pushed on both the monthly figure and how long the plan runs.
Some companies can set up a VAT payment plan online without speaking to anyone. HMRC sets the conditions and changes them from time to time, but they generally include having filed your returns, owing less than the online limit and having no other HMRC payment plan, so check the service for the current limits.
If you’re above those limits, or enforcement has already started, you’ll need to ring instead, and it helps to have these to hand:
- the VAT owed, and any other tax debts;
- why the company cannot pay;
- the monthly amount it can afford, and the date of the first payment;
- a cash-flow forecast;
- how future returns will be paid on time.
HMRC may also expect the company to raise some cash first, perhaps by selling stock or vehicles it doesn’t need, or by directors putting money in. If the company is behind on PAYE or Corporation Tax as well, a plan becomes much harder to win, because HMRC will weigh everything the company owes it, not just the VAT.
When a plan is agreed, it can cover the VAT, penalties and interest together, and it can reduce or remove the penalties. Interest keeps running on the unpaid balance until it’s cleared, though, and if a payment is missed HMRC can cancel the plan and charge the penalties as though it had never existed.
So before anyone proposes a figure, we check whether it still works once next quarter’s VAT falls due. We’d rather the offer matched what the forecast supports, even if HMRC pushes back on it, than see a larger figure agreed and then missed. A broken plan is far harder to put back together.
If HMRC refuses, or a plan collapses, stop and test whether the company is solvent before you make a second offer. Our Time to Pay guide covers the negotiation in full, and a separate page explains what happens if HMRC rejects your arrangement.
VAT Penalties and Interest If You Pay Late
Paying VAT late brings two separate charges: a late payment penalty, which steps up the longer the debt goes unpaid, and interest, which runs from the very first day. These are HMRC’s current rates, which we checked in October 2026. HMRC raised them in 2025, so older VAT periods may have been charged at lower rates.
| How late the VAT is | Penalty position | Interest position | What the director should do |
|---|---|---|---|
| Up to 15 days | No late payment penalty if you pay in full, or ask for Time to Pay in this window and HMRC agrees it | Interest accrues from the first overdue day | Pay, or get Time to Pay agreed now |
| 16 to 30 days | First penalty: 3% of the VAT owed at day 15 | Interest still accruing daily | Ask for Time to Pay to stop it rising |
| 31 days or more | First penalty 6% in total (3% at day 15 plus 3% at day 30), then a second penalty at 10% a year, accruing daily | Interest still accruing daily | Take advice; agree Time to Pay or a formal route |
The first penalty depends on when you ask for help, not how much you owe. If you ask for Time to Pay by day 15 and HMRC agrees it, £20,000 of VAT carries no penalty, but if the first call comes on day 16, £600 has already been added. Interest runs in both cases.
Interest is charged at the Bank of England base rate plus 4% a year, and agreeing Time to Pay doesn’t stop it. HMRC sets all of these figures and can change them, so check its pages on late payment penalties and late payment interest before you rely on them.
A worked example. Say a company owes £20,000 and pays 40 days late. The first penalty is £600 at day 15, and another £600 is added at day 30, so it has £1,200 in penalties before the second penalty starts.
From day 31 that second penalty runs at 10% a year on the balance, which on £20,000 is about £5.48 a day, so by day 40 the penalties have reached roughly £1,255. All the while, interest has been running on the full amount since the first day.
What Happens If VAT Arrears Remain Unpaid?
HMRC doesn’t follow a fixed timetable for VAT debts. The stages below are the usual direction of travel, but it can move faster or skip a stage depending on the account’s history and the size of the debt. Our guide to HMRC enforcement action covers each stage in more detail.
| Stage | What it means | Director action | Risk level |
|---|---|---|---|
| VAT payment missed | The debt is live from the day after the deadline, and HMRC’s system flags it | Contact HMRC now | Low, but rising |
| Reminder or demand | A penalty notice, then formal demand letters | Respond and propose Time to Pay | Medium |
| Debt management contact | The debt goes to HMRC’s debt management team, or to a collection agency acting for them | Engage and agree a plan | Medium to high |
| Payment plan discussion | HMRC may still agree Time to Pay if the business is viable | Put forward a realistic offer | Reducible |
| Enforcement or recovery | Enforcement agents under Taking Control of Goods (HMRC can seize company assets), or direct recovery from the company’s bank account | Take advice the same week | High |
| Statutory demand | A formal demand for a debt over £750. If the company does not pay, secure or compromise the debt within 21 days, the creditor can use that as evidence the company cannot pay its debts | Diary day 21: pay, agree terms or take advice before then | High |
| Winding-up petition | HMRC asks the court to close the company down; HMRC is a frequent petitioning creditor in compulsory liquidation cases | Urgent insolvency advice | Severe |
If a statutory demand arrives, you have 21 days to respond, so take advice that week rather than at the end of it. A winding-up petition can follow, and by that stage HMRC is much less ready to agree a plan.
When VAT Arrears May Mean Your Company Is Insolvent
The first thing to settle is whether the company can pay its debts as they fall due, because that is what separates a payment problem from an insolvency one. If you have one late quarter and customers who pay, you’re in a very different position from a company where VAT, PAYE and suppliers are all running behind at once.
Part of the reason VAT is so easy to fall behind on is structural. At the standard rate, £1 in every £6 a customer pays is VAT, because 20% added to the price is a sixth of the total, and a service business with few costs to reclaim owes nearly all of that to HMRC.
On a quarterly return, money received early in the quarter can sit in the bank for more than four months before it’s due: the rest of the quarter, and then a month and seven days. That’s long enough for it to start feeling like working capital, and once it has gone on wages or stock, the return arrives with nothing set aside to pay it.
Arrears can also have a more innocent cause. Unless the company uses cash accounting, it owes VAT when it raises an invoice rather than when the customer pays, so slow payers can leave it owing VAT on money it hasn’t received. If an invoice stays unpaid for six months and is written off, the VAT on it can be reclaimed through bad debt relief on a later return.
The pattern that should worry you is paying last quarter’s VAT out of this quarter’s receipts. It can look like keeping up, but it means each new bill is already short before it arrives, and every quarter starts from the same hole with penalties and interest added.
Three questions help separate a payment problem from a solvency problem. Ask all three, since a yes to the first doesn’t settle the second:
- Can the company clear the arrears in a realistic period? If yes, paying in full or Time to Pay may be suitable. If no, go to question two.
- Can it also pay the next VAT, PAYE and Corporation Tax bills when they fall due? If yes, a short-term restructuring may still work. If no, go to question three.
- Are suppliers, lenders or other creditors overdue as well? If yes, the problem may be wider cash-flow insolvency. If no, ask whether HMRC-only arrears can be settled through an arrangement the company can keep to.
If the company can neither clear the arrears nor pay next quarter’s bills, it may already be failing the cash-flow test for insolvency, and that’s the point to take professional insolvency advice. The third question then tells you how wide the problem is. Our guide on how to check if a company is insolvent sets out the legal tests.
It also matters who gets paid first if things go wrong. Since December 2020 HMRC has been a secondary preferential creditor for VAT, which put it back near the front of the queue: in the order creditors get paid in a liquidation, the VAT itself comes ahead of floating charge holders and ordinary unsecured creditors, though penalties and interest don’t.
Paying suppliers ahead of HMRC moves money to creditors who rank below it. Keeping key suppliers paid so the company can keep trading can be defended, but it does nothing to reduce what the company owes HMRC.
Can Directors Be Personally Liable for VAT Arrears?
Not automatically. VAT owed by a limited company is the company’s debt, and you don’t become personally liable as a director just because it hasn’t been paid.
Where personal exposure does arise, it comes from how the company was run, usually once it was insolvent or close to it. When a company enters liquidation, the liquidator reviews its records, including the bank statements, and asks who was paid while HMRC was not. Separately, HMRC can pursue a director personally in a limited set of cases.
A personal liability notice passes on a penalty for deliberate wrongdoing or evasion. A joint liability notice goes further and can make a director liable for the company’s tax itself, for example where they were involved with repeated insolvent companies that left tax unpaid and now run a similar business. Beyond that, the main risks are these:
- Trading on. If you keep trading after you knew, or should have known, that insolvent liquidation could not be avoided, a liquidator can ask the court for a personal contribution for wrongful trading.
- Selective payments. A liquidator can look back six months at payments to creditors who are not connected to the company, and two years at payments to connected people, such as directors and their families. Paying suppliers to keep trading is easier to defend than repaying yourself, a relative or a bank debt you’ve guaranteed, and dividends taken when the company couldn’t pay its debts can also be challenged, under separate rules.
- Using unpaid VAT as working capital. Not paying tax that’s owed is one of the kinds of conduct the Insolvency Service lists when it considers disqualification.
- Thin records. Without notes made at the time, it’s much harder to show that your decisions were reasonable.
The same conduct is what the Insolvency Service weighs when it decides whether to seek a director’s disqualification, and our page on what happens to directors in liquidation explains how a liquidator’s review works.
One question we ask early is whether the company is in a VAT group, because every member of a group is jointly liable for the group’s VAT. That means a sister company’s arrears can be recovered from yours.
What Are the Company’s Options If It Cannot Clear the VAT Debt?
The options differ mainly in who stays in control. Time to Pay and refinancing leave the company as it is, a Company Voluntary Arrangement keeps the directors in charge but binds the company to a supervised deal with its creditors, and administration and liquidation hand control to an insolvency practitioner.
For VAT in particular, a Company Voluntary Arrangement can’t reduce the VAT itself without HMRC’s agreement, because VAT is preferential. Penalties and interest are not, so they can be dealt with alongside the other unsecured debts. Which routes are actually open depends on whether the business is viable at its current size.
| Option | When it fits | Main risk | Next step |
|---|---|---|---|
| Pay in full or Time to Pay | The company is viable and can afford the payments | HMRC may decline and resume enforcement | Call HMRC before you miss an instalment |
| Short-term refinancing | The VAT problem is temporary and repayment is genuinely affordable | Adds borrowing the business cannot service if it is not viable | Check the borrowing is serviceable first |
| Company Voluntary Arrangement | A viable company that needs a formal repayment deal with creditors | Needs creditor approval, and HMRC’s preferential ranking for VAT limits what a CVA can do without its agreement | Take advice from a licensed insolvency practitioner |
| Company Administration | There may be a rescue or a sale, or serious creditor pressure | Control passes to an administrator | Move quickly; options narrow under petition pressure |
| Creditors’ Voluntary Liquidation | The company cannot recover | Ends the company, and director conduct is reviewed | Take advice on an orderly closure |
Because we’re a licensed insolvency practice, a first conversation with us is about working out which of those two you’re dealing with: a payment-plan problem or a solvency problem. It’s free and confidential, and where a rescue is still possible, the earlier it happens the more options remain open.
Frequently Asked Questions
Can I pay VAT in instalments?
Often, yes, through a Time to Pay arrangement. Call HMRC’s payment support line on 0300 200 3835 with a realistic repayment proposal, before enforcement starts.
Will HMRC charge penalties if I cannot pay VAT?
Yes, from day 16 if you have neither paid nor had Time to Pay agreed. The first penalty is 3% of the VAT owed at day 15, rising to 6% in total after day 30, and a second penalty then accrues at 10% a year. Interest is charged on top of all of this, and the penalty table above has the detail.
Can HMRC close my company for unpaid VAT?
Yes. HMRC can ask the court to wind up your company, meaning close it down, for an undisputed debt of more than £750, and sometimes for less if it can show the company cannot pay its debts. A statutory demand is one route to a petition, not a precondition.
Can directors be personally liable for unpaid VAT?
Not automatically. VAT is normally a company debt. Personal exposure depends on conduct, such as wrongful trading, where you kept trading after you knew, or should have known, that insolvent liquidation could not be avoided.
HMRC can also pursue a director in limited cases, set out in the section above.
Can I get business funding to pay VAT?
If the business is viable and the shortfall is temporary, short-term funding can clear the VAT and replace an HMRC debt with a commercial one on terms you control. It only makes sense if the business can service the borrowing. Using finance to prop up a company that is not viable adds borrowing it cannot service.
When should I speak to an insolvency practitioner?
When the VAT debt is more than a realistic Time to Pay plan can clear, when HMRC has refused or cancelled a plan, or when a statutory demand arrives.
Not Sure Where Your Company Stands?
Use the two-minute test to check the warning signs and see how soon you may need to act.
Check my company’s positionEstimates are fineWe only call if you ask us to