


What are the Warning Signs of an Insolvent Company?



You are sitting with three quarters of management accounts open on the laptop and the pattern is hard to miss. Cash out has exceeded cash in for nine consecutive months.
PAYE is a fortnight late, your factor has quietly trimmed the advance rate from 85% to 70%, and two of your regular suppliers have moved you to pro-forma. The question you are really asking is not “is this bad?” but “is this legally insolvent, and what does that mean for me personally?”
Insolvency is not a feeling, it is a statutory test. Section 123 of the Insolvency Act 1986 defines it in two ways.
The company cannot pay its debts as they fall due (the cash-flow test), or its liabilities exceed its assets on a “point of no return” analysis (the balance-sheet test, per BNY Corporate Trustee Services v Eurosail [2013] UKSC 28). You cross that line well before a winding-up petition lands.
The warning signs below are the ones we see first when a director rings us. The sooner you recognise where you are on that curve, the more options you still have, and the lower the risk of personal liability under section 214 wrongful trading.
The First Warning Signs of an Insolvent Company: Cash Flow
The earliest indicator is the Friday BACS run you start to dread. You have the list of suppliers open in one tab and the bank balance in another, and you are sequencing payments by who will shout loudest rather than who is contractually due. That is not a liquidity hiccup, it is a structural mismatch between working capital and obligations.
Concrete patterns to watch for:
- The overdraft is at its ceiling every month-end rather than only in the dip before a big receipt.
- You are paying rolling PAYE from current-month sales rather than from funds set aside the month before.
- You have started asking suppliers for 60-day terms on invoices you used to clear in 14.
- Directors’ loans are going in, not coming out, and the board has stopped discussing when they will be repaid.
None of those is fatal on its own. Three of them together, running for two quarters, is a strong sign that the company may already be cash-flow insolvent under section 123(1)(e): unable to pay its debts as they fall due. That test does not wait for anything to be filed.
See our guide to company cash flow problems for the triage sequence we run with directors on a first call. At that stage, the board often has not modelled a 13-week cash-flow in three months, and the director is treating the overdraft ceiling as working capital rather than as a debt facility.
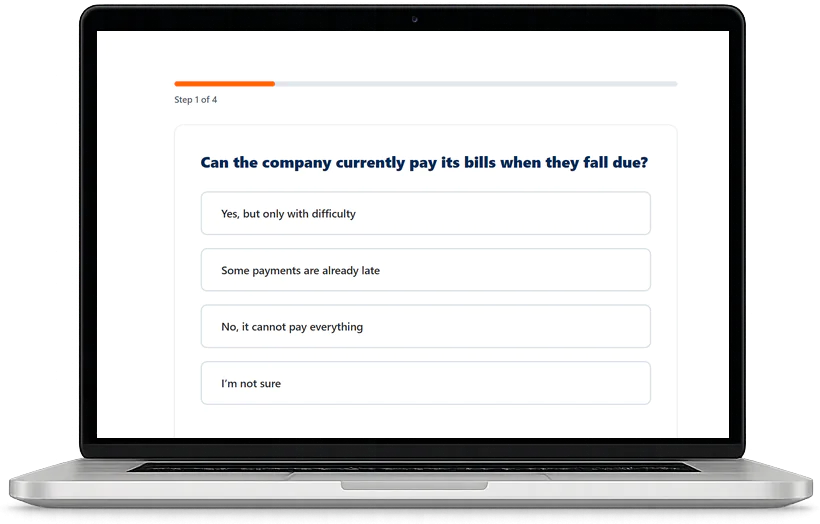
Could Your Company Be Insolvent?
Answer four short questions to see which warning signs apply, how serious the position may be and how soon you may need to act.
See which options may fit your company’s circumstances.
Check my company’s positionSee your result online and receive a copy by email. We only call if you ask.
Warning Signs of Insolvent Trading: The Creditor Letters Change Tone
Creditor pressure has a recognisable arc. First come reminder statements that look like the old ones. Then comes a “final demand” printed in red, usually with a seven-day deadline that is actually fourteen.
Then comes the statutory demand: a specific legal instrument under section 123(1)(a) of the Insolvency Act 1986, claiming a debt over £750, with 21 days for the company to pay, secure, or compromise before the creditor can petition to wind up.
A statutory demand is not a bluff. Ignore it and on day 22 your creditor can present a winding-up petition to the court on the ground that the company is deemed unable to pay its debts. Our note on statutory demands against a company sets out the defences and the tight deadline for challenging one.
The other tonal shift happens in the phone calls. Once a creditor’s in-house credit team hands your file to external solicitors or a commercial debt collector, the correspondence becomes standardised.
Bland letterhead, formal language, threats quoted verbatim from pre-action protocols. The danger sign there is not the letter itself. It is that the human relationship you had with the accounts manager is gone, and that relationship is hard to get back once the file has been outsourced.
HMRC Arrears: The Most Lethal Warning Sign of Insolvency
HMRC is the creditor most companies treat casually and it is the one most likely to push a viable business into compulsory liquidation. Three HMRC-specific indicators every director should audit monthly:
- PAYE or VAT slipping by more than one filing period. One missed quarter is a cash-flow wobble. Two missed quarters is a pattern, and HMRC’s late-payment interest now runs at the Bank of England base rate plus 4 percentage points.
- A Time to Pay arrangement that has been refused or defaulted. HMRC will entertain a TTP once, sometimes twice. A third approach after a broken previous arrangement rarely lands.
- A Field Force visit or a “seven-day letter” from Debt Management. These are the pre-petition steps. By the time you see one, the file has been escalated internally.
Since the Finance Act 2020 reinstated Crown preference on 1 December 2020, HMRC ranks as a secondary preferential creditor for VAT, PAYE, employee NIC, and CIS. That changes the economics of any rescue.
A floating-charge lender now sits behind HMRC for those taxes, so the usual “bank will lend against the book” escape route is narrower than it was. Our note on HMRC threatening letters unpacks the typical escalation path.
Warning Signs of Insolvency in the Ledger and Books
Two diagnostic lines on the trial balance tell an IP more than a page of commentary. First, the aged debtors report: if debtors over 90 days have grown as a percentage of total debtors for three months running, you have a collections problem that is being masked by new billing.
Second, the aged creditors. If the list is growing and the oldest entries are HMRC and the pension scheme, you are at the stage where every new sale makes the hole deeper, not shallower.
The quieter signal is the one directors miss. The bookkeeper pushing management accounts back a month, then two, then producing figures that always look “provisional”. Late management accounts can be a sign that the finance team knows what the numbers will show.
If you have not seen a full management pack (P&L, balance sheet, cash-flow forecast) in the last six weeks, that is itself a warning sign. A director who signs a set of accounts in those conditions is the director a liquidator writes to under section 214, which asks when the director knew, or ought to have concluded, that insolvent liquidation or administration could not reasonably be avoided.
When Suppliers and Insurers Move First: Warning Signs from the Outside
The earliest external signal is trade credit drying up. Your wholesaler quietly halves your credit limit. The trade insurer who used to cover your largest customer rings to say they are reviewing the cover.
Your invoice discounter moves from 85% advance to 70%, then to a daily notification regime where every invoice is pre-approved. These are not administrative changes. They are credit decisions taken by people who have seen your Experian file and your filed accounts.
You will often get the news from a sales rep, not from a formal letter. The rep says “head office has pulled credit” and moves on. It is the director’s job to treat that call as a data point on par with a Companies House filing, not a personality problem to negotiate around.
Directors tend to focus on the noisy creditor: the HMRC envelope, the supplier threatening court. The dangerous creditor is usually the quiet one. The landlord who stops responding to emails because they have instructed surveyors to value the unit for forfeiture, or the bank relationship manager who has been replaced by “the recoveries team” without announcement.
The Legal Warning Signs of an Insolvent Company: CCJs and Petitions
A County Court Judgment (CCJ) against the company is a public event. It appears on the Registry Trust record within days, credit agencies pick it up within a week, and your suppliers’ credit-risk teams will see it before you have finished deciding whether to appeal. Two or more unsatisfied CCJs is, in practice, how most trade creditors’ systems reclassify you as high-risk.
The next step up is the winding-up petition. Once presented, two things happen almost immediately. The petition is advertised in The Gazette, which banks monitor electronically.
Once the advert appears, banks usually freeze the company account quickly, because of section 127 of the Insolvency Act 1986: if a winding-up order is made, any disposition of company property after the petition was presented is void unless the court validates it.
Once the petition is advertised in the Gazette, the bank usually freezes the account. Our guide to CCJs against a limited company walks through the five working days between petition and Gazette in detail.
Bailiffs at the door are the late-stage symptom rather than the early warning. By the time a High Court Enforcement Officer is attending premises, a judgment has been obtained and a writ of control issued.
If that is where you are, the window for a controlled insolvency process has narrowed sharply. A conversation with a licensed IP within 24 hours is not a precaution, it is a necessity.
Warning Signs of Insolvency and the Duty Shift Under Sequana
Directors running a solvent company owe their duties to the company’s members, as codified in section 172 of the Companies Act 2006. Once the company is on the brink of insolvency, the Supreme Court in BTI 2014 LLC v Sequana SA [2022] UKSC 25 confirmed that directors must also consider the interests of creditors as a whole, and balance them against shareholders’ interests.
The duty shifts before formal insolvency. It arises when directors know, or ought to know, that the company is insolvent or bordering on insolvency, or that an insolvent liquidation or administration is probable. A liquidator does not read board minutes to find what was decided, they read them to find what was not.
The practical consequence is this. The moment you recognise two or three of the warning signs above, you need to minute that recognition, record the board’s assessment, and start taking decisions with creditor interests weighted alongside shareholder ones. A liquidator reading board minutes eighteen months later is looking for exactly that shift in framing, not for evidence of heroism.
Section 214 of the Insolvency Act 1986 provides the bite. If at some point before winding-up you knew, or ought reasonably to have concluded, that there was no reasonable prospect of avoiding insolvent liquidation or insolvent administration, and you did not take every step to minimise the loss to creditors, you can be ordered to contribute personally to the estate.
The clock on “ought to have concluded” starts running the day the warning signs became unmistakable, not the day you rang an IP. Our page on the statutory insolvency test explains how IPs reconstruct that timeline.
Your Next Step on the Warning Signs of an Insolvent Company
The honest verdict is this. If you have recognised one warning sign you have a cash-flow problem. If you have recognised three or more and they have persisted for two quarters, you have a directors’ duties problem. The first is commercial and you can probably trade through it. The second is legal and it does not resolve by itself.
Directors split into two camps on that call. If your company has a genuine prospect of recovery, a live order book, a lender willing to re-facilitate, a one-off loss that is behind you, your next step is a documented board review with advice on file. That paper trail is the section 214 defence.
If you cannot honestly tell yourself there is a reasonable prospect of avoiding insolvent liquidation, your next step is a formal conversation with a licensed IP this week, not next month.
Call Company Debt free on 0800 074 6757 for a confidential review with one of our licensed insolvency practitioners. We will walk through the section 123 test against your actual numbers, tell you where you sit on the section 214 curve, and set out whether a CVA, a moratorium, an administration, or a creditors’ voluntary liquidation is the right route. Nothing is charged until you instruct us.
Not Sure Where Your Company Stands?
Use the two-minute test to check the warning signs and see how soon you may need to act.
Check my company’s positionEstimates are fineWe only call if you ask us to
FAQs on Warning Signs of an Insolvent Company
What is the legal definition of an insolvent company in England and Wales?
Section 123 of the Insolvency Act 1986 sets the tests. A company is “unable to pay its debts” if it has failed to satisfy a statutory demand over £750 for 21 days, if an execution against it is unsatisfied, if it cannot pay its debts as they fall due (cash-flow test), or if liabilities exceed assets on a “point of no return” basis (balance-sheet test per Eurosail). Any one limb triggers the Act.
What are the earliest warning signs of insolvency?
Persistent overdraft use at the ceiling, PAYE or VAT slipping by a filing period, aged debtors over 90 days growing for three months running, and suppliers withdrawing credit. Any two of those persisting across two quarters is a directors’ duties issue, not a cash-flow wobble.
What happens if a director ignores the warning signs of insolvency?
Section 214 of the Insolvency Act 1986 allows a liquidator to pursue the director personally for the increase in net deficiency caused by continued trading after the point at which a reasonably diligent director ought to have concluded there was no reasonable prospect of avoiding insolvent liquidation or insolvent administration. Disqualification under the CDDA 1986 is a separate parallel risk.
Does a statutory demand mean the company is insolvent?
Not automatically, but an unpaid statutory demand over £750 that has been outstanding for 21 days is deemed evidence of inability to pay debts under section 123(1)(a). The creditor can then present a winding-up petition.
A company cannot apply to set aside a statutory demand: that 18-day procedure is for individuals. If the debt is genuinely disputed on substantial grounds, act before the 21 days run out: tell the creditor in writing and, if needed, ask the court for an injunction to stop a winding-up petition.
When does the Sequana duty shift kick in?
The Supreme Court in BTI v Sequana [2022] held that directors must have regard to creditors’ interests when they know, or ought to know, that the company is insolvent or bordering on insolvency, or that an insolvent liquidation or administration is probable. It is not tied to the formal section 123 threshold; in practice it bites as soon as the warning signs are clustering.
Can a company trade through insolvency?
Sometimes, if the directors can show that trading on is the step that best minimises creditor loss. In practice that means a documented board decision and professional advice on file.
Without them, trading on after the point where there was no reasonable prospect of avoiding insolvent liquidation or administration is hard to defend against a section 214 wrongful trading claim. A CVA or a moratorium is often the formal way to trade through.



