

How Can I Stop or Avoid Insolvency?



It is 10pm. The management accounts are open on one screen, an HMRC letter on another, and a half-drafted email to the factoring company in between. You have been round the numbers twice tonight and the answer each time has been “next week’s payroll does not work”. That is the moment most directors first Google “how to avoid insolvency”.
The honest starting point is that “avoid” is sometimes the wrong word. Some companies can be turned around before the balance sheet fails; others cannot, and the director has not yet accepted the diagnosis. The job of this page is to set out both routes, the informal ones that keep you out of formal process, and the formal ones that stop insolvency from running to its full conclusion.
Below, we cover the turnaround moves available before the tipping point, the statutory tools that freeze the situation, and the point at which continuing to fight is itself a breach of duty. Companies that recover usually act fast: they call a specialist as soon as the management accounts show payroll will not clear.
What It Means to Stop or Avoid Insolvency
A company is insolvent in law when it fails the cash-flow test or the balance-sheet test in section 123 of the Insolvency Act 1986. The cash-flow test asks whether you can pay your debts as they fall due; the balance-sheet test asks whether your liabilities exceed your assets, taking account of contingent and prospective liabilities.
“Avoiding” insolvency means acting early enough that neither test is failed. “Stopping” insolvency means using a formal tool to halt the consequences once the tests are being failed. The two routes look similar from the outside but are legally different.
Once your company is insolvent, or close to it, you must take creditors’ interests into account.
Under BTI 2014 LLC v Sequana SA [2022] UKSC 25, your duty is still owed to the company, but creditors’ interests carry more weight the worse the position gets. They become paramount once insolvent liquidation or administration is unavoidable. Decisions from that point can be reviewed against whether you gave creditors’ interests proper weight.
Could Your Company Be Insolvent?
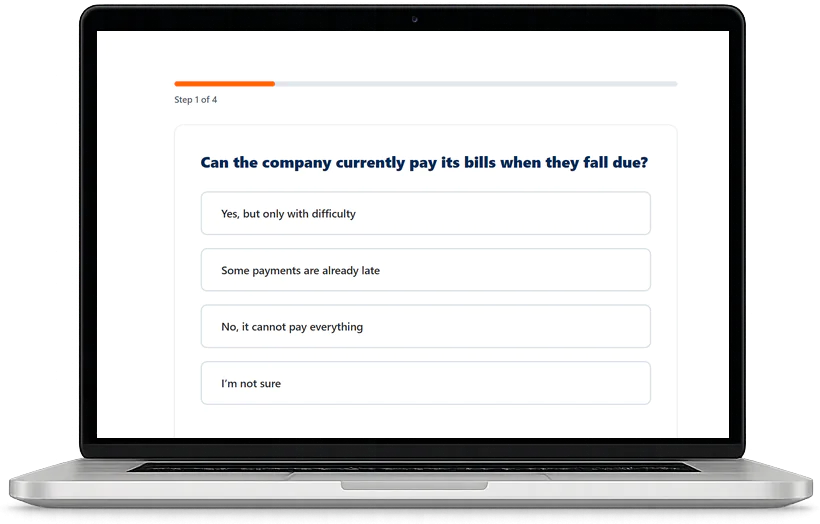
Answer four short questions to see which warning signs apply, how serious the position may be and how soon you may need to act.
See which options may fit your company’s circumstances.
Check my company’s positionSee your result online and receive a copy by email. We only call if you ask.
Early-Stage Turnaround Options Before Formal Insolvency
These are the levers you can pull before the section 123 tests are failed. They are the tools that actually avoid insolvency rather than stopping it:
- Time to Pay (TTP) with HMRC, an agreed instalment plan for Corporation Tax, VAT, or PAYE arrears. Arranged directly with HMRC’s Business Payment Support Service, typically 6 to 12 months, longer on BBL-related VAT.
- Invoice finance or factoring, advances against sales ledger to bridge the gap between billing and payment. Fast, but it costs a percentage per invoice and ties up your debtor book.
- Asset sale-and-leaseback, releasing capital tied up in machinery or vehicles, with the asset financier taking the book value and renting it back to you.
- Director capital injection or shareholder loan, direct cash support, documented as a loan or a subscription for shares.
- Equity raise or trade investor, slower but non-refundable capital, suitable where there is a genuine growth story to sell.
- Debt restructuring with lenders, renegotiating repayment schedules, interest holidays, or amortisation profile on commercial lending.
- Pay As You Grow on Bounce Back Loans, the repayment extensions and payment holidays lenders offer on BBLs under the 2020 scheme rules.
Early-stage options share a trade-off. Invoice finance keeps you trading but tethers you to a factoring fee structure that compounds month on month. A director loan helps with this week’s payroll but adds to the overdraft on the director’s loan account you will have to explain later. Each option buys time, and the quality of what you do with the time decides the outcome.
Negotiating with HMRC: Time to Pay Arrangements
HMRC is the single largest creditor in most SME insolvencies, and it is also the most structured to negotiate with. A Time to Pay arrangement, applied for through the Business Payment Support Service, can spread arrears over 6 to 12 months, sometimes longer.
HMRC will typically agree TTP where you can show:
- Cash-flow projections for the period covering the instalments, prepared on a reasonable basis.
- Evidence the cause of the arrears was transitory, a lost customer, a bad debt, a supply-chain disruption, rather than structural.
- Current-period returns are up to date, HMRC will normally expect the current VAT return to be filed before it agrees TTP on overdue VAT.
- You have explored other funding, bank facility, director loan, equity, and cannot cover the bill from those sources.
Interest continues to run on TTP at the standard HMRC late-payment rate (Bank of England base rate plus four percentage points since 6 April 2025). A second TTP after a first has defaulted is much harder to land. HMRC’s position hardens markedly once its Debt Management team has transferred the case to enforcement, so the call you make matters.
Formal Tools That Can Stop Insolvency Short: CVA and Moratorium
When the informal options are exhausted but the business is still viable, two formal tools can halt the slide into full liquidation or administration:
- Company Voluntary Arrangement (CVA), a statutory compromise with creditors under Part 1 of the Insolvency Act 1986. Requires 75% creditor approval by value of those voting, and fails if more than half (by value) of the unconnected creditors vote against it. Pays a compromised amount over a fixed period, typically three to five years, after which the remaining debt is written off.
- Part A1 Moratorium, the standalone moratorium introduced by the Corporate Insolvency and Governance Act 2020. Gives you a 20-business-day breathing space (extendable) with a freeze on most creditor action while a restructuring plan is developed. Requires a licensed insolvency practitioner as monitor.
A CVA works where the business model is fundamentally viable but the legacy debt is not affordable. It leaves the directors in place, preserves trading relationships, and avoids the stigma of liquidation. The trade-off is that creditors holding more than 25% by value of the votes cast can defeat the proposal, and HMRC often votes against unless the offer is strong.
The moratorium is newer, less tested, and more complex. It is most useful when you need a narrow window to land a refinancing, sale, or CVA, rather than as a standalone solution. The qualifying conditions exclude companies with recent insolvency history, so it is not a universal tool.
How to Stop a Winding-Up Petition Before It Becomes an Order
A creditor who is owed more than £750 and whose debt is undisputed can serve a statutory demand and, after 21 days, petition for your company’s winding-up. The petition is advertised in the London Gazette at least seven business days after it is served on the company.
If a winding-up order is made, section 127 of the Insolvency Act 1986 makes any disposition of company property after the petition was presented void unless the court orders otherwise.
The window between presentation and advertisement is the one where you can still act effectively:
- Pay the petition debt in full, if the funds exist. This removes the statutory basis for the petition.
- Negotiate a withdrawal, with settlement terms and costs paid. Before the petition is advertised, the petitioning creditor can ask the court for permission to withdraw it. After that, a settled petition is normally dismissed at the hearing.
- Contest the petition, where the debt is genuinely disputed on substantial grounds. The Mann v Goldstein line of authority sets the test.
- Propose a CVA or administration that offers creditors a better outcome than liquidation.
Once the petition is advertised, the practical window closes. The bank will freeze the account on notice. Suppliers will pull credit. Your factoring facility will typically suspend. Applying for a validation order under section 127 is possible, but it is a rearguard action rather than a fix.
When to Stop Fighting and Use Formal Process
The difficult judgement for directors is not “can I avoid insolvency?” but “when does continuing to fight make things worse?”.
Section 214 of the Insolvency Act 1986 creates civil liability for wrongful trading. A director who continues trading after the point at which there was no reasonable prospect of avoiding insolvent liquidation can be personally liable for the increase in creditor losses from that date.
The markers that usually mean “stop”:
- Payroll is at risk for consecutive months, not just a single late payment.
- HMRC arrears are increasing, not decreasing, despite TTP attempts.
- The order book has fallen below break-even and there is no realistic prospect of recovery in the next quarter.
- Trade credit has been withdrawn by one or more major suppliers.
- A key customer or contract has been lost without replacement.
Two of those markers together is enough for us to recommend an urgent meeting with a licensed insolvency practitioner. Three is the point at which continuing to trade without advice becomes the risk itself.
The option that looks like “giving up” may actually protect the most jobs and the most creditor value, because a creditors’ voluntary liquidation caught early preserves optionality that a winding-up order does not.
Your Next Step on Stopping or Avoiding Insolvency
The numbers on the screen matter, but so does how fast you act on them. Two groups read this page, and your next call is different.
- If you are in the early stage and no petition has been issued, you have options. Call an insolvency practitioner for a diagnostic this week, not next month. A CVA, TTP, or refinancing lands when the business is still viable; a fortnight later, the same conversation is about liquidation.
- If a petition has been presented or advertised, you are no longer in “avoid” territory, you are in “contain”. Do not make selective payments. Do not sign over assets. Apply for a validation order if essential trading payments must continue, and take specialist advice inside 48 hours.
Our licensed IPs can review the cash position, diagnose whether a turnaround is realistic, and arrange a CVA, moratorium, or orderly liquidation where appropriate. Call us free on 0800 074 6757 for confidential advice.
Not Sure Where Your Company Stands?
Use the two-minute test to check the warning signs and see how soon you may need to act.
Check my company’s positionEstimates are fineWe only call if you ask us to
FAQs on Stopping or Avoiding Insolvency
Can I stop a winding-up petition after it has been advertised?
Yes. Options include paying the petition debt, agreeing a settlement with the petitioning creditor so the petition is dismissed, contesting it on substantial-dispute grounds, or putting the company into administration through a court application.
Once advertised, the bank account will typically be frozen. If a winding-up order is made, section 127 of the Insolvency Act 1986 makes any disposition since the petition was presented void unless the court validates it.
Is a CVA a good way to avoid liquidation?
A CVA works where the business is fundamentally viable but the legacy debt cannot be serviced. It requires approval by 75% by value of the creditors who vote, and fails if more than half by value of the unconnected creditors vote against it. It typically runs for three to five years, and leaves directors in place.
It is not suitable where the order book has collapsed or the trading model itself is broken. HMRC, which ranks as a secondary preferential creditor for debts such as VAT and PAYE income tax, often votes against weak CVA proposals.
How long does a Time to Pay arrangement take to agree with HMRC?
Straightforward TTPs under £100,000 are often agreed within a single phone call to the Business Payment Support Service and a follow-up cash-flow submission. Larger or more complex cases can take several weeks and may require accountant or IP support. HMRC will normally expect current-period returns to be up to date before it agrees TTP on older arrears.
At what point does continuing to trade become wrongful trading?
Under section 214 of the Insolvency Act 1986, a court can order you to contribute towards the increase in creditor losses from the point at which there was no reasonable prospect of avoiding insolvent liquidation. That is a judgement call, not a bright-line test.
Taking contemporaneous licensed insolvency advice, and documenting the alternatives considered, is the strongest defence if a liquidator reviews the decision later.
Can I use a Part A1 moratorium without a CVA?
Yes, but rarely sensibly. The moratorium is most useful as a 20-business-day breathing space in which to land a refinancing, sale, CVA, or scheme of arrangement. Used without a clear plan for what happens when the moratorium ends, it simply delays the formal process.
Will taking early insolvency advice trigger formal process?
No. A diagnostic conversation with a licensed IP is confidential and non-obligatory. Some companies go on to trade out through informal turnaround rather than a formal process. Early advice expands your options; late advice narrows them.